
Roofing insurance supplements are requests for additional payment on a claim when the insurer’s original estimate leaves out work or materials the job requires. Gaps like this are common on storm jobs, because the adjuster usually writes the estimate from a short inspection before anyone has torn off a shingle. For a small crew, getting paid for those items depends on keeping measurements, photos, and paperwork organized, and that’s where insurance claim tracking in a roofing CRM earns its keep.
What a Supplement Is and Why Claims Need Them
An adjuster’s estimate is a scope of work with a price attached to each line. Most carriers write it in Xactimate after an inspection that may last less than an hour. From the ground or a quick walk of the roof, the adjuster can’t see the decking, may miss a second layer of shingles, and may not know what the local building code requires on a reroof.
A supplement asks the carrier to add or correct line items once those facts are known. It doesn’t open a new claim, and it doesn’t dispute coverage. It revises the scope, with evidence that the added work is necessary to finish the repair the carrier already approved.
Items Adjusters Commonly Leave Out
The same line items come up on claim after claim. A contractor who checks for them on every insurance job will catch most of the missing money before the work starts.
- Starter strip and ridge cap, which sometimes get priced as field shingles or left off the estimate
- Drip edge and ice and water shield where local code requires them
- Step flashing, counter flashing, and pipe boots that can’t be reused
- Steep-slope and two-story labor charges
- Tear-off of a second or third layer of shingles
- Rotted or damaged decking found after tear-off
- Permit fees and code upgrades, which depend on the policy carrying ordinance and law coverage
- Detaching and resetting gutters, satellite dishes, or solar panels
- Overhead and profit on jobs that involve several trades
Not every item applies to every roof, and each one needs its own proof. A carrier won’t pay for ice and water shield because a contractor says it’s standard practice. It will pay when the request cites the code section that requires it.
How to Document Roofing Insurance Supplements
Start with a line-by-line comparison. Put the adjuster’s estimate next to the contractor’s own scope and mark every difference in quantity, material, or labor. Quantity errors are the easiest to prove. If the adjuster measured 24 squares and an aerial measurement report shows 27, the report settles it. RoofIT integrates with EagleView, so that report can sit on the job with the rest of the claim file.
Photos carry most of the remaining items. Take them before tear-off, during it, and after, and get both a wide shot that shows where on the roof the problem is and a close shot that shows the condition. Decking is the one that catches crews out. Once new underlayment covers a rotted sheet of plywood, the only evidence left is whatever someone photographed that morning.
For code items, include the code section and the jurisdiction that adopted it. Manufacturer installation instructions help with items such as starter strip and ridge cap, since they show what the shingle maker requires. Material invoices back up pricing when a carrier questions it.
Send the supplement in a format the carrier’s desk reviewer can process quickly. Line items should match the structure of the original estimate, each with a short reason and a reference to the photo or document that supports it. Then log the date it went out and set a follow-up, because supplements that nobody follows up on tend to sit.
What a Contractor Can and Can’t Do on a Claim
Many states limit who may negotiate an insurance claim on a policyholder’s behalf to licensed public adjusters and attorneys. A roofing contractor can document damage, explain the scope and cost of the repair, and send the carrier evidence for it. Arguing about what the policy covers is a different activity, and in some states it can put a contractor’s license at risk.
The rules differ from state to state, so it’s worth checking with the state insurance department or an attorney before setting a company process. Keeping the homeowner copied on supplement correspondence is good practice everywhere. The claim belongs to them, and carriers often need their consent to discuss it.
Where Small Crews Lose Supplement Money
A roofing company with one to ten employees doesn’t have a supplement department. The owner or a salesperson writes supplements at night, after a day of estimates and installs, and the claim file is spread across three phones, an email inbox, and a folder in the truck.
Money goes missing in predictable places. The crew finds bad decking and replaces it, but nobody takes a photo. A supplement goes out and no one calls the carrier again. The carrier approves an extra $1,800 three weeks after the job closes, and the final invoice has already gone out at the original amount. None of these are estimating mistakes. They happen because the estimate, the photos, the carrier’s paperwork, and the invoice live in different places.
Tracking Supplements in RoofIT
RoofIT Solutions was started by Douglas Stroh, who grew Gold Medal Roofing to multiple locations in several states and found that the CRMs available weren’t made for small roofing businesses. RoofIT is built by roofers for roofers, and it’s designed for small roofing crews, not corporate offices.
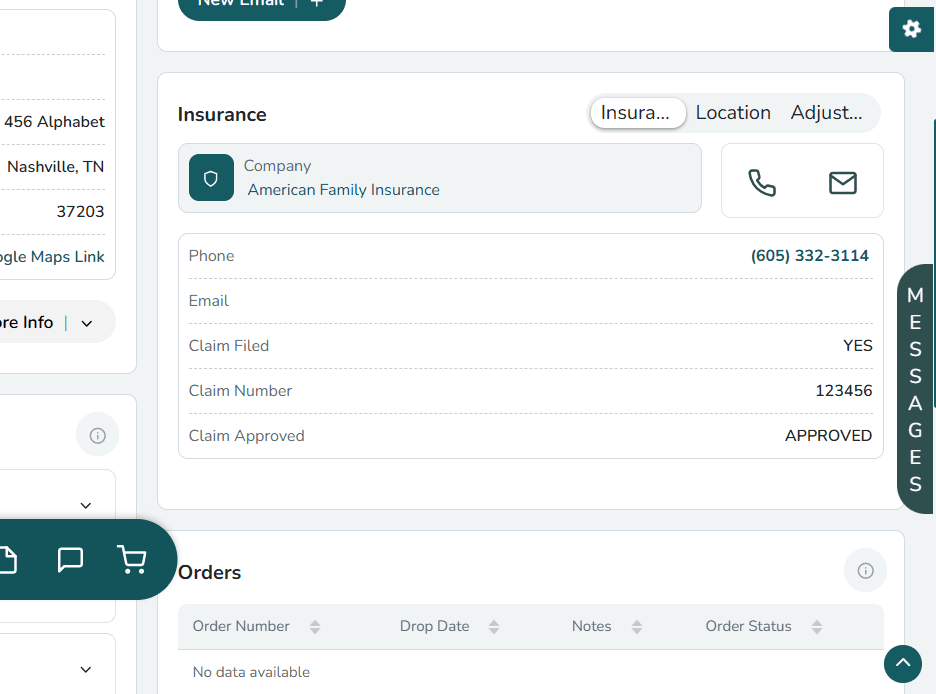
For insurance work, that comes down to keeping the claim on one job record. The contractor’s scope comes from the roofing estimator tools, and the photos, carrier documents, and notes stay with the job where the whole crew can find them. When a carrier approves a supplement, the revised total has to reach the customer’s invoice, and billing and invoicing in RoofIT works from that same job. An owner handling roofing insurance supplements alone can see which ones are still waiting on a carrier without digging through email.
RoofIT is free for two months with no credit card required. Request a demo or start the trial and run the next insurance job through it.
